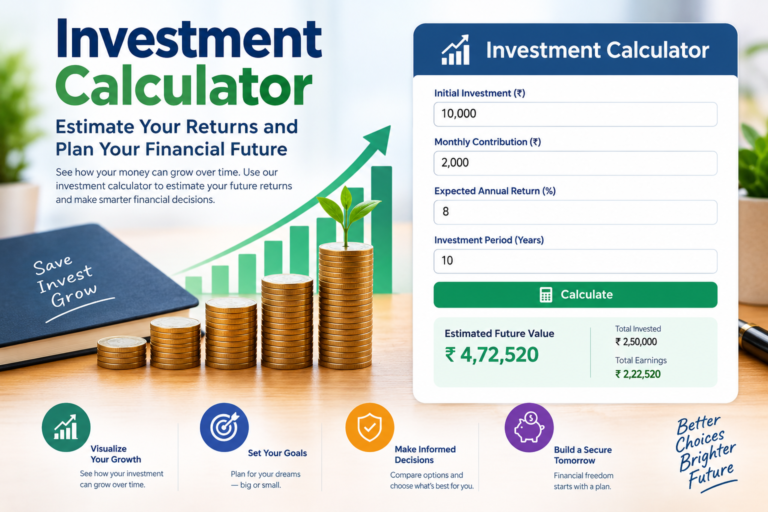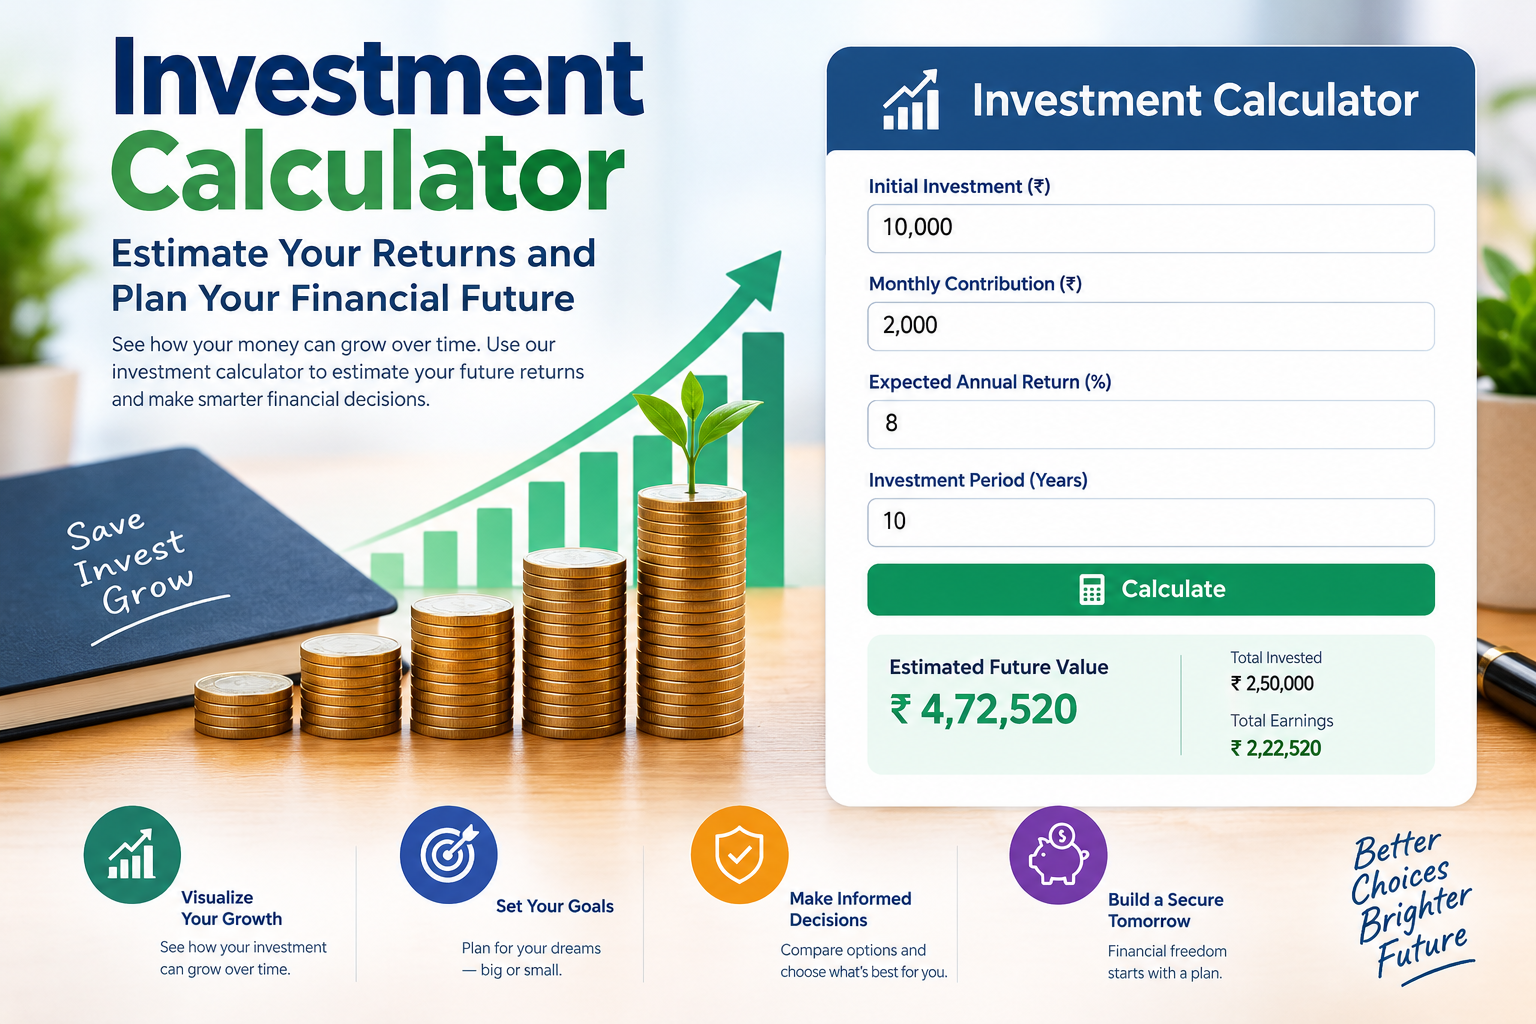
Investment Calculator
Planning your financial future becomes easier when you understand how your money can grow. An investment calculator helps you estimate future savings, possible profits, and long-term investment growth. It gives you a simple way to explore different financial goals before investing your money. You can change your starting amount, monthly contributions, expected return, and investment period. The results help you understand how these choices may affect your future wealth.
You do not need advanced math skills to use this helpful tool. Even beginners can use it to plan for a house, education, retirement, or other important goals. However, remember that calculator results are estimates, not promises. Real investments can rise or fall in value. Fees, taxes, inflation, and market changes can also affect your final amount. This guide explains how investment calculators work, how to use them, and how to understand their results. You will also discover practical examples, common mistakes, and useful tips for making better financial decisions.
What Is an Investment Calculator?
An investment calculator is an online tool that estimates how your money might grow over time. It uses details such as your starting investment, regular deposits, expected annual return, and investment duration. After you enter these values, the tool estimates your future balance. Some calculators also show your total contributions and estimated investment earnings separately.
For example, imagine you invest $1,000 and add $100 every month. You expect an average annual return of 6% and plan to invest for ten years. A calculator can estimate the possible value of your investment at the end of that period. You can then change the monthly contribution or time frame to compare different outcomes. This makes financial planning easier and more practical. The result depends on your assumptions, so it should never be treated as guaranteed income. A calculator is best used as a planning guide rather than a promise of future wealth.
How Does an Investment Calculator Work?
An investment calculator uses a mathematical formula to estimate how your money may increase. It considers your initial deposit, additional contributions, expected return, and investment period. Some tools calculate simple growth, while others include compound interest. More advanced versions may also account for inflation, taxes, investment fees, and different contribution schedules.
The basic process is simple. You enter your financial details and choose a suitable time frame. The calculator then applies your expected rate of return to estimate future growth. If you contribute regularly, the tool includes those deposits in its calculation. For example, monthly investments may grow faster than a single deposit because new money enters your account throughout the year. However, the actual return may change from month to month. Most calculators use fixed assumptions to keep their results easy to understand. Therefore, try different return rates and investment periods to see how sensitive your plan is to changing conditions.
Why Should You Use an Investment Calculator?
An investment calculator helps turn a financial goal into a clearer plan. Instead of guessing how much money you might need, you can estimate the amount required to reach your target. It also helps you understand the relationship between time, regular savings, and potential growth. These details can help you make more informed choices.
Suppose you want to save $50,000 within 15 years. You can enter your current savings and estimated return to see whether your plan looks realistic. If the projected balance falls short, you might increase your monthly contributions or extend your timeline. You could also compare different return assumptions to understand possible outcomes. The tool can support retirement planning, education savings, emergency fund goals, and other long-term plans. Still, avoid choosing investments based only on the highest projected return. Risk, affordability, and your personal needs matter just as much. Use the calculator to explore options, then research the investments themselves.
Understanding Compound Interest and Investment Growth
Compound interest occurs when you earn returns on your original money and on previous earnings. Over time, this process can help an investment grow faster. The effect becomes more noticeable when you invest for many years. This is why starting early can be useful, even when your initial contributions are small.
Consider an investment of $5,000 earning an assumed annual return of 7%. With annual compounding and no additional deposits, the investment could grow to approximately $9,836 after ten years. After 20 years, it could reach around $19,348. These figures assume a steady return and exclude taxes, fees, and inflation. Real investments rarely produce identical returns every year. Some years may bring gains, while others may bring losses. An investment calculator can help you explore this long-term effect. It also shows why patience and regular contributions can matter. However, compound growth does not remove investment risk or guarantee a positive result.
How to Calculate Your Future Investment Value
You can estimate investment growth using a mathematical formula. For a single deposit with annual compounding, the formula is:
Future Value = Present Value × (1 + r)ⁿ
In this formula, present value means your starting investment. The letter r represents the annual return written as a decimal. The letter n represents the number of years. For example, a $2,000 investment growing at an assumed 5% annually for five years would become approximately $2,553. This calculation assumes the return stays constant and earnings remain invested. If you add money every month, the calculation becomes more complex because each deposit has a different growth period. A suitable calculator can handle these details automatically. Always check whether your chosen tool compounds monthly, annually, or at another interval. Different assumptions can produce different results, even when the displayed annual return remains the same.
How to Use an Investment Calculator Step by Step
Using an investment calculator is usually quick and straightforward. You only need a few details about your financial plan. Begin with your current investment amount, if you already have savings. Next, enter the amount you expect to contribute regularly. Choose a realistic annual return based on the investment type you are researching. Then select how many years you want your money to remain invested.
Review the result after entering your information. Look for the estimated future balance, total contributions, and projected earnings. If the tool offers different scenarios, compare conservative, moderate, and optimistic assumptions. For example, you could test monthly contributions of $50, $100, and $150. This comparison can help you choose a savings amount that fits your budget. Do not invest money needed for essential expenses simply to reach a calculator target. Your plan should remain affordable and flexible. Revisit your estimates when your income, goals, or financial responsibilities change. Regular reviews can keep your plan aligned with your real circumstances.
Investment Calculator Example: Monthly Contributions
Regular contributions can make a meaningful difference to long-term investment growth. Imagine you start with $1,000 and contribute $100 each month for ten years. Assume an annual return of 6%, compounded monthly, with deposits made at each month’s end. Under these assumptions, your estimated balance would be about $17,600. Your total contributions would equal $13,000, including the original deposit. The remaining amount would represent estimated investment growth before fees, taxes, and inflation.
This example shows how regular saving and investment earnings can work together. It does not mean you will receive the same result in a real investment account. Market returns change, and some investments may lose value. Your actual balance could be higher or lower than the estimate. You can use an investment calculator to test different monthly amounts and time frames. Try increasing your contribution gradually when your income rises. Even a small increase can affect the final projection over many years. Choose a contribution level you can maintain without putting essential spending at risk.
Types of Investment Calculators You Can Use
Different calculators serve different financial needs. A basic investment growth calculator estimates the future value of a starting amount. A compound interest calculator focuses on how earnings build over time. A monthly investment calculator estimates growth from regular contributions. Each option can help you understand a different part of your financial plan.
You may also find retirement calculators, stock return calculators, mutual fund calculators, and inflation calculators. Retirement tools estimate whether your savings may support future living costs. Stock calculators help compare purchase prices and possible returns, although they cannot predict market performance. Mutual fund tools estimate growth based on selected assumptions. Inflation calculators show how rising prices can reduce purchasing power. Some tools combine several features in one place. Before using any calculator, check the assumptions and information it requires. Select a tool that matches your goal instead of relying on a complicated calculator with features you do not need. Clear inputs usually produce more useful planning insights.
How Inflation Affects Your Investment Returns
Inflation means that prices rise over time, reducing what your money can buy. An investment may increase in value while losing some purchasing power. This is why looking only at your final account balance can give an incomplete picture. You should also consider how living costs may change during your investment period.
For example, imagine your investment earns an average annual return of 7%, while inflation averages 3%. Your approximate annual return after inflation would be about 3.9%, before taxes and fees. This is called the real return. The calculation uses the relationship between investment growth and price increases rather than simply treating the full 7% as additional purchasing power. An investment calculator with an inflation feature can help you compare future money with today’s prices. This is especially useful for long-term goals, such as retirement or education. Inflation rates can change, so test several assumptions. Planning for inflation can help you set a more realistic target and understand the value of future savings.
Investment Fees, Taxes, and Their Impact on Returns
Investment fees and taxes can reduce the amount of money you keep. Some investments charge management fees, trading costs, account fees, or other expenses. These charges may seem small, but their effect can increase over many years. Taxes may also apply to interest, dividends, or investment gains, depending on your country and account type.
When using an investment calculator, check whether it includes these costs. If it does not, your displayed balance may be higher than your actual after-cost result. You can test a lower annual return to explore how expenses might affect growth. However, this is only an approximation, not a replacement for a detailed fee calculation. Tax rules vary by location and investment type. Review the relevant rules before making financial decisions. Compare investment products by considering their total costs, risk, and features. A product with impressive projected returns may not be the best choice if its fees are high or its risks exceed your comfort level.
Choosing a Realistic Expected Rate of Return
The expected rate of return is one of the most important inputs in an investment calculator. It represents the annual growth rate you assume for your investment. A higher rate produces a larger projected balance, while a lower rate produces a smaller one. However, choosing a high number simply to reach your goal can create unrealistic expectations.
Different investments have different levels of risk. Cash savings, bonds, stocks, and diversified funds can behave very differently. Their returns also depend on market conditions, interest rates, fees, and investment periods. Historical performance can provide context, but it cannot guarantee future results. Instead of relying on one optimistic estimate, calculate several scenarios. Use a cautious assumption alongside a moderate estimate and a more optimistic case. This helps you understand the range of possible outcomes. Your time frame and ability to handle losses should guide your decisions. If you are unsure which assumptions are appropriate, consider speaking with a qualified financial adviser who understands your circumstances.
Common Investment Calculator Mistakes to Avoid
An investment calculator is useful, but incorrect inputs can lead to misleading results. One common mistake is assuming that an investment will earn the same return every year. Real markets fluctuate, and losses can occur. Another mistake is forgetting to include fees, taxes, or inflation. These factors can reduce your future purchasing power and final balance.
Some people also underestimate the importance of regular contributions. Others assume that a larger projected balance automatically means a better investment. Both approaches can overlook important details. A risky investment may offer greater potential growth but could also experience larger losses. Make sure your contribution amount fits your budget and your timeline matches your goal. Check whether the calculator assumes monthly or annual deposits. Review whether returns are compounded and when contributions are added. Finally, remember that projections are estimates rather than financial guarantees. Use the results to compare choices, ask better questions, and improve your plan instead of treating them as certain predictions.
Investment Planning Tips for Beginners
Starting an investment plan does not require a large amount of money. The first step is understanding your goals and deciding how much you can afford to invest. Build a suitable emergency fund and address expensive debt before committing money to long-term investments. These steps can reduce the chance of needing to sell investments during a difficult period.
Next, learn about different investment options and their risks. Diversification means spreading your money across different investments rather than relying on one asset. It can reduce the impact of poor performance in a single holding, although it cannot eliminate all risk. Consider your time frame, financial responsibilities, and comfort with market changes. Use an investment calculator to compare regular contributions and possible growth rates. Review your plan periodically instead of reacting to every market movement. If you need personal advice, consult a qualified professional. The best plan is one you understand, can afford, and can follow consistently over time.
Frequently Asked Questions About Investment Calculators
1. What is an investment calculator used for?
An investment calculator estimates how your money may grow over a chosen period. It uses details such as your starting balance, regular contributions, expected return, and investment duration. The result can help you compare savings plans and estimate progress toward financial goals. However, it cannot guarantee profits or predict future market movements. Use it as a planning tool and remember that actual results may differ from the displayed estimate.
2. Is an investment calculator accurate?
An investment calculator can perform accurate mathematical calculations when its inputs and formulas are correct. However, its future projections depend on assumptions that may not match real market conditions. Investment returns can change, and costs may affect your balance. Treat the result as an estimate rather than a promise. For better planning, compare several return rates and include fees, taxes, and inflation whenever possible.
3. How much should I invest every month?
The right monthly amount depends on your income, expenses, debt, emergency savings, and financial goals. Start with an amount you can afford without missing essential payments. You can increase contributions when your financial situation improves. A calculator can show how different monthly deposits might affect future growth. Avoid choosing a contribution simply because it creates an attractive projection. Your plan should remain manageable throughout your investment period.
4. Can an investment calculator show compound interest?
Yes, many investment calculators include compound interest calculations. These tools estimate how your original investment and accumulated earnings may grow together. Some also include regular deposits, which can increase the projected balance over time. Check the calculator’s compounding frequency and contribution schedule. Remember that real investment returns are not always steady, so actual growth may differ from the calculation.
5. Does an investment calculator account for inflation?
Some calculators include an inflation setting, while basic tools may not. Inflation affects purchasing power because goods and services can become more expensive over time. If your calculator excludes inflation, its future balance may look more valuable than it will feel in real terms. Compare the projected balance with an estimate of future living costs. This can help you set a more practical financial target.
6. Can beginners use an investment calculator for free?
Yes, many online investment calculators are free and designed for beginners. Most require only a starting amount, expected return, contribution schedule, and investment period. You do not need advanced financial knowledge to understand the basic results. Choose a calculator that clearly explains its assumptions and does not require unnecessary personal information. Before investing, research the investment itself and understand the risks involved.
Conclusion
An investment calculator can make financial planning easier by showing how savings, contributions, and estimated returns may work together. It helps you compare different strategies and understand the possible effects of time and compound growth. You can use it to plan for retirement, education, a home, or other important goals. The most useful results come from realistic assumptions and regular reviews.
Remember that projections cannot remove investment risk or guarantee future wealth. Consider inflation, fees, taxes, and changing market conditions before making decisions. Start with a clear goal and an affordable contribution amount. Then test several scenarios to understand your options. As your circumstances change, update your calculations and adjust your plan when needed. Small, consistent steps can support better financial habits over time. Have you used an investment calculator to plan a financial goal? Share your experience or questions, and keep learning as you build your financial future.
About the Author